Digital Arrest Scams 2026: Victim Compensation & UPSC
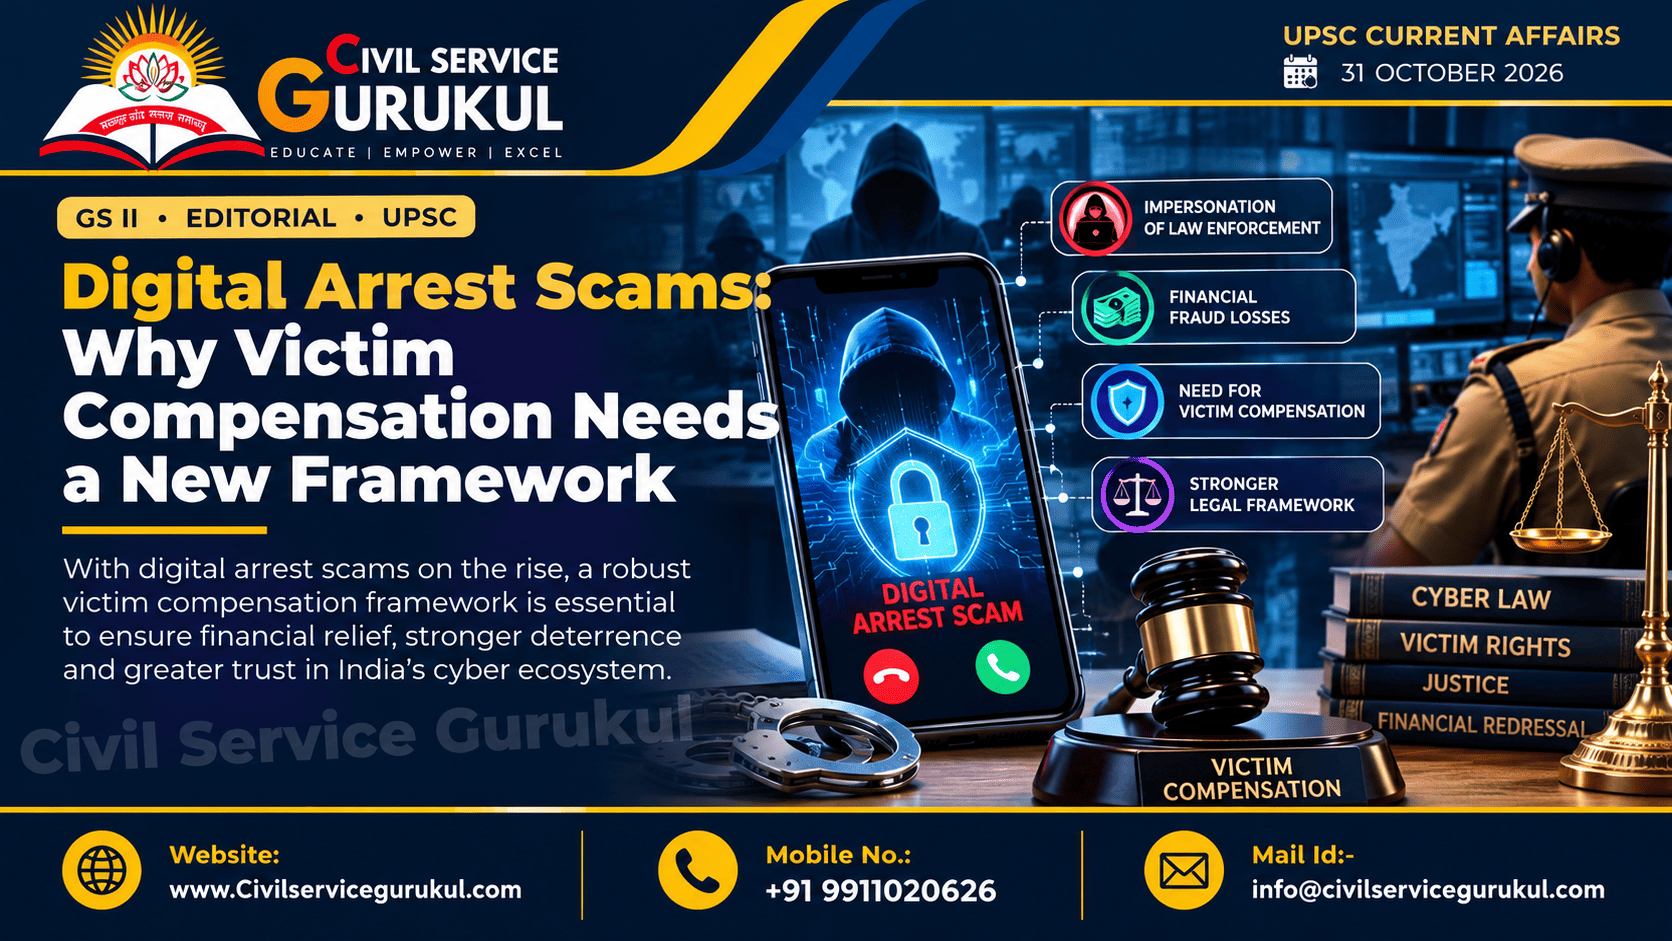
Digital Arrest Scams in India 2026: Why Victims Need a Fair Compensation and Cybercrime Protection Framework
An in-depth analysis of impersonation-based cybercrime, financial fraud, victim compensation, banking accountability, digital evidence and India's cybersecurity governance.
Digital arrest scams are a form of cyber-enabled fraud in which criminals impersonate police officers, investigators or regulatory officials to intimidate individuals into transferring money.
Victims may be falsely told that they are under investigation or must remain connected to a video call until a supposed inquiry has been completed.
These incidents raise questions about victim compensation, financial-system accountability, law-enforcement coordination and protection against psychological coercion.
India requires a victim-centred response that combines rapid reporting, effective investigation, fair liability standards and accessible grievance redressal.
GS Paper II: Government policies, institutional accountability, citizen protection, grievance redressal and access to justice.
GS Paper III: Cybersecurity, internal security, technology-enabled crime and financial-system resilience.
GS Paper IV: Ethical governance, compassion, fairness, responsibility and protection of vulnerable citizens.
Prelims: Cybercrime reporting, institutional mandates, digital fraud, mule accounts and cybersecurity terminology.
Why Are Digital Arrest Scams in the News?
A newspaper topic listed on 30 October 2026 highlighted judicial concern regarding compensation for victims of digital arrest fraud.
The discussion brings attention to a major gap between reporting a cybercrime and obtaining meaningful financial relief.
Although prompt reporting may help authorities trace or freeze suspicious funds, it does not guarantee that the victim's money will be recovered.
A discussion about creating a new compensation framework must not be confused with the enactment of a legally binding universal reimbursement scheme.
The supplied material does not establish that every victim is automatically entitled to compensation.
What Is a Digital Arrest Scam?
A digital arrest scam involves criminals pretending to be law-enforcement or government officials and using threats to extort money.
The perpetrators may claim that a person's identity, bank account or mobile number has been linked to criminal activity.
They may then demand immediate payment under the pretext of verification, security deposits or avoiding prosecution.
Is Digital Arrest a Legal Procedure?
No. The expression "digital arrest" describes a fraudulent impersonation tactic.
A video call or online message claiming that someone has been arrested does not by itself constitute a lawful arrest.
How Do Digital Arrest Scams Operate?
Stage 1: Initial Contact
The victim receives a call or message from someone claiming to represent a police agency, financial regulator or investigative authority.
Stage 2: Fabricated Allegations
The caller may falsely allege money laundering, identity misuse or another serious offence.
Stage 3: Psychological Pressure
Fraudsters may use uniforms, forged documents, official-looking backgrounds or video calls to create fear.
Stage 4: Isolation
Victims may be instructed not to contact family members, lawyers or other authorities.
Stage 5: Financial Transfer
The fraudsters demand money transfers to supposed verification or security accounts.
Stage 6: Movement of Funds
Stolen money may be moved through multiple accounts, making tracing and recovery more difficult.
India's Existing Cybercrime Reporting Framework
National Cyber Crime Reporting Portal
India provides a national online mechanism for reporting cybercrime.
Citizens can report suspected online fraud and provide information relevant to investigation.
1930 Cybercrime Helpline
The 1930 helpline is intended for prompt reporting of financial cybercrime.
Early reporting can assist coordination between relevant authorities and financial institutions.
Role of Banks
Banks may assist through transaction information, fraud reporting, account monitoring and actions required under applicable procedures.
Role of Law Enforcement
Police and investigative agencies may examine digital evidence, trace suspicious transactions and pursue criminal proceedings according to law.
Reporting through the helpline or portal does not automatically replace all other legal or procedural requirements.
Victims should follow the directions provided by competent authorities regarding formal complaints and investigation.
Why Does Victim Compensation Need a Better Framework?
A major policy concern is that financial loss may continue even after a fraud has been reported.
Criminal prosecution, recovery of stolen money and compensation are distinct processes.
Financial Recovery
Recovery refers to retrieving funds that can be identified and lawfully restored through applicable procedures.
Compensation
Compensation concerns financial relief provided under an applicable legal, contractual or policy framework.
Institutional Accountability
A fair framework should examine whether an institution failed to comply with a relevant duty.
However, the mere fact that a fraudulent transfer occurred does not automatically establish negligence by a bank.
Who Should Bear Responsibility for Cyber Fraud Losses?
| Stakeholder | Possible Responsibility | Important Safeguard |
|---|---|---|
| Fraudsters | Criminal responsibility for fraudulent acts | Evidence-based investigation and due process |
| Banks | Compliance with applicable security and customer-protection duties | Liability based on relevant facts and law |
| Other Intermediaries | Compliance with applicable legal obligations | Proportionate accountability |
| Government | Investigation, coordination and public protection | Transparent administration and legal safeguards |
| Victim-Assistance Mechanism | Potential financial relief if established by law or policy | Clear eligibility, verification and review |
The central challenge is to design a framework that protects victims without imposing arbitrary or unlimited liability on institutions.
Major Challenges in Investigation and Compensation
Mule Accounts
Fraudsters may use accounts controlled or made available by other individuals to receive and transfer stolen money.
Rapid Fund Transfers
Funds may move through multiple accounts before reporting occurs.
Cross-Border Networks
Some cybercrime networks operate across jurisdictions, complicating investigation and enforcement.
Delayed Reporting
Victims may hesitate to report fraud because of fear, embarrassment or uncertainty.
Digital Evidence
Investigations may require preservation of transaction records, messages, call details and other electronic evidence.
Moral Hazard
Poorly designed blanket reimbursement arrangements could create incentive and verification problems.
Such concerns should be addressed through appropriate safeguards, rather than denying genuine victims access to fair remedies.
Way Forward: A Victim-Centred Cybercrime Compensation Framework
- Develop clear and transparent standards for determining institutional negligence.
- Improve rapid reporting and coordination between relevant agencies.
- Strengthen procedures for lawful and timely account-freezing requests.
- Provide time-bound grievance decisions with written reasons.
- Introduce accessible appeal and independent review mechanisms.
- Improve preservation of digital evidence.
- Expand multilingual public-awareness programmes.
- Ensure that vulnerable victims can obtain appropriate assistance.
- Consider carefully designed victim-support mechanisms, subject to legal authority, funding and eligibility rules.
- Publish anonymised performance indicators on reporting, recovery and grievance resolution.
Phased Implementation
A reform programme could begin with clear standards and pilot mechanisms.
Independent evaluation could then assess administrative feasibility, victim outcomes, financial sustainability and unintended consequences.
What Should Citizens Do When Targeted by Digital Arrest Fraud?
- Do not transfer money merely because a caller claims to be an official.
- Do not disclose OTPs, passwords or banking credentials.
- End suspicious calls and independently verify claims through official channels.
- Contact the bank promptly if a financial transfer has occurred.
- Report financial cybercrime through the 1930 helpline.
- Submit a complaint through the National Cyber Crime Reporting Portal.
- Preserve relevant messages, transaction details and available evidence.
- Follow the instructions of competent authorities regarding further legal action.
No genuine law-enforcement procedure requires a person to transfer money to a caller's account to avoid a supposed "digital arrest."
UPSC Prelims Practice Questions
Question 1
Which of the following statements is correct?
(a) Police may legally arrest a citizen through any ordinary video call.
(b) Rapid reporting of financial cybercrime may assist fund tracing.
(c) All cyber fraud victims are automatically reimbursed.
(d) The 1930 helpline automatically replaces every formal legal complaint.
Prompt reporting can help authorities coordinate financial tracing and appropriate action. It does not guarantee recovery or reimbursement.
Question 2
Consider the following statements:
- Digital arrest is a recognised ordinary legal procedure conducted entirely through video calls.
- Fraudsters may impersonate law-enforcement officials to intimidate victims.
Which of the statements given above is/are correct?
(a) 1 only
(b) 2 only
(c) Both 1 and 2
(d) Neither 1 nor 2
Statement 1 is incorrect. Digital arrest is a term used for a fraudulent impersonation tactic.
Statement 2 is correct because impersonation and intimidation are central features of such scams.
Question 3
Which of the following best describes a mule account in the context of financial cybercrime?
(a) An account used only for government salary payments
(b) An account used to receive or move funds on behalf of another person, potentially including fraud proceeds
(c) An account that cannot receive electronic transfers
(d) An account exclusively maintained by the central bank
Mule accounts can be used to receive and move fraud-related funds, complicating financial tracing.
Question 4
Which of the following is most appropriate for a fair cyber fraud compensation framework?
(a) Automatic unlimited liability for every bank in every fraud case
(b) Denial of all relief whenever the victim initiated a transfer
(c) Evidence-based liability, clear eligibility rules and accessible grievance review
(d) Compensation without any verification process
A fair framework should balance victim protection, institutional accountability, verification and due process.
UPSC Mains GS Paper II and III Practice
Question: "Cybercrime governance must move beyond criminal prosecution towards effective victim protection." Discuss with reference to digital arrest scams, financial recovery, institutional accountability and due process. (250 words)
Suggested Answer Framework
Introduction: Define digital arrest scams as impersonation-based cyber-enabled financial fraud.
Institutional Framework: Discuss cybercrime reporting, banks and investigative agencies.
Victim Protection: Explain emergency reporting, fund tracing, financial recovery and grievance redressal.
Challenges: Highlight mule accounts, cross-border operations, delayed reporting and evidence preservation.
Governance Concerns: Discuss proportionate liability, institutional negligence, moral hazard and due process.
Way Forward: Recommend transparent standards, inter-agency coordination, independent review and multilingual awareness.
Conclusion: Effective cybercrime governance requires a balance between deterrence, fair compensation, institutional accountability and citizens' rights.
Frequently Asked Questions
Is digital arrest legal in India?
No. Digital arrest is a term commonly used for a fraudulent impersonation tactic, not an ordinary lawful mode of arrest.
What is the 1930 helpline?
It is India's national helpline for reporting financial cybercrime.
Can cyber fraud victims recover their money?
Recovery may be possible depending on the facts, timing of reporting, availability of funds and applicable procedures. It is not guaranteed.
Are banks automatically liable for all digital arrest scams?
No. Liability depends on the applicable legal and regulatory framework and the specific facts of the case.
What should a victim do first?
Contact the bank promptly, report financial cybercrime through 1930 and preserve relevant evidence.
Why is this topic important for UPSC preparation?
It connects governance, internal security, cybersecurity, financial regulation, access to justice and ethical administration.
Key Takeaway for UPSC Aspirants
Digital arrest scams demonstrate that cybersecurity is not merely a technical issue. It is also a challenge of institutional trust, financial protection, citizen awareness and public accountability.
A credible policy response must improve prevention, investigation and recovery while providing fair and legally sustainable remedies for victims.
SEO Keywords and Tags
Prepare for UPSC with Civil Service Gurukul
Strengthen your understanding of governance, internal security, cybersecurity, public policy, ethics and current affairs through concept-based UPSC examination preparation.
Website: www.civilservicegurukul.com
Mobile: +91 9911020626
Email: info@civilservicegurukul.com
Prepare with Mentors Who Cleared the Exam
Get personalized study plans, evaluated answer models, and test series access.